

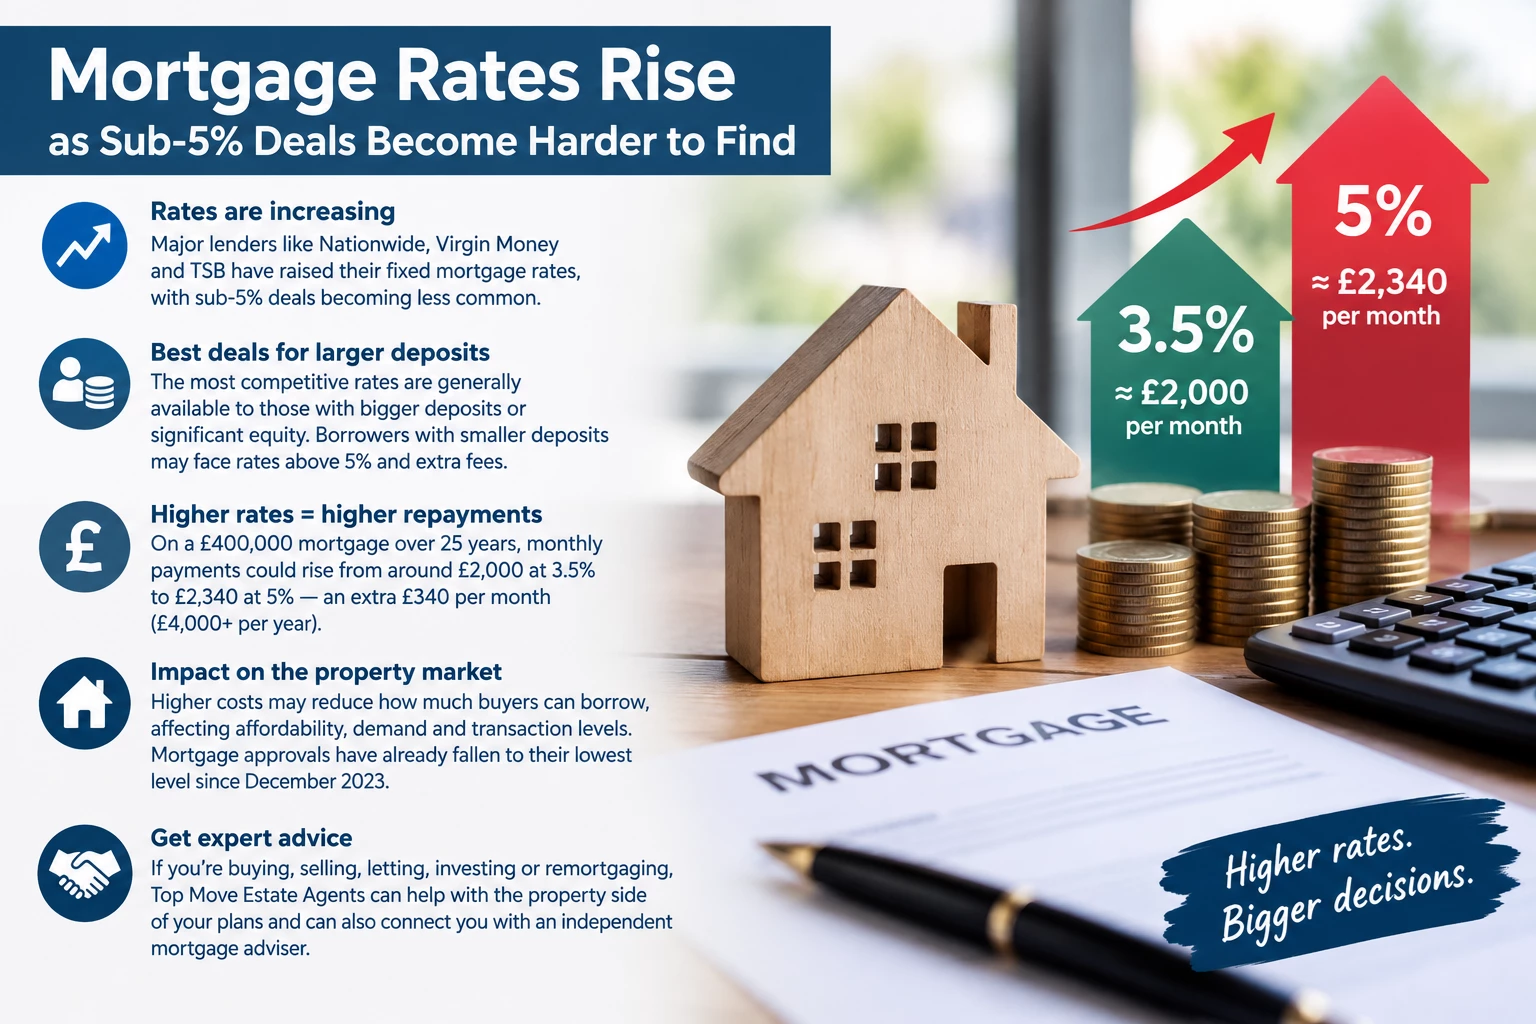
Mortgage borrowers are facing a changing market as a growing number of lenders increase their fixed mortgage rates.
Several major lenders, including Nationwide, Virgin Money and TSB, have recently adjusted their pricing. As a result, mortgage products carrying interest rates below 5% are becoming increasingly limited.
This represents a noticeable change from earlier in the year, when some borrowers were able to secure fixed-rate mortgages at considerably lower rates.
Fewer competitive fixed-rate deals available
The most competitive mortgage rates are now generally available to borrowers with larger deposits or substantial levels of equity in their homes.
Some lenders are still offering fixed-rate products below 5%, but the choice is becoming more restricted and arrangement fees may also apply.
Borrowers with smaller deposits may find that the rates available to them are above the 5% level.
For buyers, landlords and homeowners approaching the end of an existing fixed-rate deal, this means it is becoming increasingly important to consider the overall cost of borrowing rather than looking at the headline interest rate alone.
What could higher rates mean for borrowers?
Even a relatively small increase in the mortgage interest rate can make a significant difference to monthly repayments. For example, on a repayment mortgage of £400,000 over 25 years, payments at an interest rate of around 3.5% would be approximately £2,000 per month.
At a rate of approximately 5%, repayments could increase to around £2,340 per month.
That represents an increase of roughly £340 each month, or more than £4,000 over a year.
The precise figure will, of course, depend on the mortgage amount, term, interest rate, fees and individual circumstances.
What does this mean for the property market?
Higher mortgage costs can affect how much buyers are able or willing to borrow, which may also influence affordability, property demand and transaction levels.
Recent mortgage-market data has indicated a reduction in mortgage approvals for house purchases, reflecting some of the affordability pressures currently affecting buyers. The source article states that approvals had fallen to their lowest level since December 2023 news.
For prospective buyers, investors and homeowners considering a remortgage, reviewing mortgage options early may therefore be worthwhile.
Planning to buy, sell or invest?
At Top Move Estate Agents, we continue to monitor developments in the property and mortgage markets so that our clients can make informed decisions.
If you are considering buying, selling, letting or investing in property, our team can assist with the property side of your plans and, where appropriate, you can also obtain independent mortgage advice from a suitably authorised mortgage adviser.
Please note: Mortgage rates and products can change at short notice. The information above is provided for general information only and does not constitute mortgage, financial or investment advice.


